Preview
Related Post
Construction Accident ClaimsConstruction Accident Claims
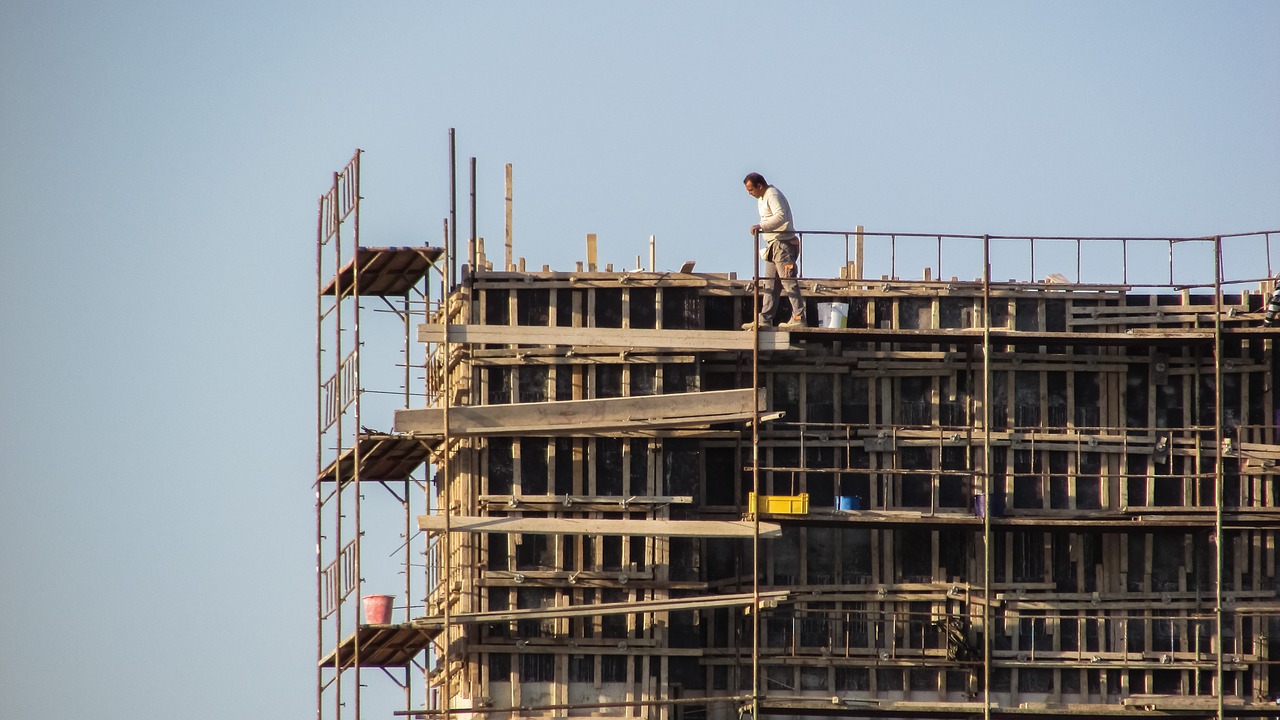 Construction jobs can be very lucrative. But the number of risks associated with construction jobs are vast. While construction workers put on their safety gear before setting out to work, most of them are wary of the fact that accidents are the order of the day. And despite their adherence to workplace safety regulations, construction jobs remain claim top spot as far as the occurrence of accidents is concerned.
It is no wonder that construction accident cases are quite common. While most of the accidents recorded lead to minor injuries, some employees are injured so severely that they are forced out of employment. That said, here are some of the most common construction accident claims recorded in legal circles.
Workers Compensation Claims
Well, while accidents happen at the construction site, then it is evident that these case should be filed through the worker’s compensation system. To receive benefits under workers compensation, the injured person bears the responsibility of proving that the injury occurred during their official working hours. The benefits attached to workers compensation claims, however, do not often cater for lost income or wages.
Personal Injury Cases
These claims are often brought out the worker’s compensation system. Personal injury claims apply when the injuries suffered were caused by a negligent third party. This could be a contractor managing the project or a vendor offering a service on the site. 
Product Liability Claims
There are incidences when a faulty tool or utility injures an employee. When this happens, the blames often falls squarely on the manufacturer or a party in the chain of distribution. Product liability claims are equally complex, considering that need to be well versed with both the technical and legal dimensions of the case.
Wrongful Death Cases
Some accidents at the construction site end up claiming lives. As much as they might not be severe, someone has to be held responsible for the loss, especially when there was an element of negligence from a third party. In this case, the victim’s family or dependents are responsible for pursuing compensation on that person’s behalf.
Tips on How to Hire the Best Ohio LawyersTips on How to Hire the Best Ohio Lawyers
Hiring a good lawyer may be one of the most crucial steps toward winning your legal case. However, finding a competent and experienced one may prove to be challenging and a difficult task, especially if it’s your first time. It’s, therefore, important to take your time and focus your research effort on finding the best lawyer who has handled similar legal issues in the past.
Because there are many benefits that come from hiring the best Ohio lawyers, it’s important that you consider the following tips when choosing one.
1. Determine What Type of Lawyer You Need
 It’s always necessary to know what your needs are before hiring just any lawyer for your case. For instance, it’s preferable to choose a lawyer with relevant experience in the legal field, particularly where your case involves. Bear in mind that there are several different types of lawyers who specialize in different legal fields, such as criminal law, family law, bankruptcy law and malpractice law just to mention a few. It’s always a good idea to hire a lawyer familiar with the laws and courts of the state or area you live in.
2. Contact Your Local Bar Association
Contacting the local bar association for qualified and experienced lawyers in your area can also help you find the best lawyer in Ohio. These state bar associations usually keep public records about disciplinary actions and complaints taken against any lawyer licensed to practice within your area. Most of these associations also offer free referral services, which can help you find the best lawyer to suit your specific case’s needs.
3. Get Recommendations and References
You can also get recommendations and referrals from your family, relatives, or even friends. If you know someone who has had a similar case before and hired a certain lawyer to represent him/her, you can ask them to recommend that particular lawyer for you. However, you should first find out more about the lawyer, the type of service offered and any other relevant information. In fact, a recommendation is the best way to find the best Ohio lawyer.
4. Check The Credentials Of The Various Ohio Lawyers
 Credentials are also one of the effective ways to find the best Ohio lawyers that you need. Good credentials help you to evaluate the professional appropriateness and competence of a lawyer for your case. Although simple membership in any professional organization may not matter a lot, active participation, especially in the work of such organizations, indicates that the lawyer is involved in the specialty.
Other better indicators of good reputation, experience, and competence include publishing books, articles, and treatises.
Always consider these pointers when looking to hire the best Ohio lawyers. Lastly, you should also define your budget before starting looking for one.
Mistakes People Make When Seeking to Improve Their Financial StatusMistakes People Make When Seeking to Improve Their Financial Status
Many aspire to improve their financial status, but the journey is often fraught with common mistakes derailing progress. Some seemingly insignificant blunders can prove fatal, preventing you from effectively using using your resources or even fully grasping the idea behind the Iman Gadzhi monk mode. Understanding and learning to avoid these pitfalls is necessary for long-term financial stability and growth. Here are some common mistakes people make when trying to improve their financial status and how to avoid them.
Having No Clear Financial Plans
One of the biggest mistakes people make is not having a clear financial plan. Without a roadmap, it’s easy to lose sight of financial goals and spend money impulsively. A well-thought-out financial plan includes setting specific, measurable, achievable, relevant, and time-bound (SMART) goals, budgeting, and creating a strategy for saving and investing. This plan should be regularly reviewed and adjusted to stay on track.
Accumulating High-Interest Debt
Relying heavily on credit cards and other forms of high-interest debt can severely impact financial health. Many people make the mistake of using credit to fund lifestyles they cannot afford, leading to mounting debt that becomes difficult to repay. To avoid such scenarios, prioritize paying off high-interest debt as soon as feasible and refrain from incurring additional debt. Using credit responsibly and within your means is key to maintaining a healthy financial status.
Failing to Save and Invest
Another common mistake is failing to prioritize saving and investing. Many people focus solely on immediate financial needs and neglect long-term financial goals. Establishing an emergency fund, contributing to retirement accounts, and investing in diversified portfolios are essential to building wealth and securing financial stability.
Ignoring the Importance of Budgeting
Budgeting is fundamental to financial management, yet many people neglect it. Without a budget, tracking income and expenses accurately is challenging, leading to overspending and insufficient savings. Building and sticking to a budget helps ensure you live within your means, allocate funds to savings and investments, and identify areas where you can cut costs.
Not Seeking Professional Financial Advice
Navigating the complex world of finance without professional guidance can lead to costly mistakes. Financial advisers can offer useful insights and tailored methods to help you accomplish your financial objectives. They may help with tax preparation, investment strategy, retirement planning, and more. Investing in professional financial advice can save you money in the long run and ensure you make informed financial decisions.
Overlooking the Importance of Financial Education
Many people make decisions based on misinformation or lack of knowledge, leading to poor financial outcomes. Investing time in financial education can empower you to make better financial decisions. Read books, attend workshops, and follow credible financial news and advice to enhance your understanding of personal finance.
Making Emotional Financial Decisions
Emotions can cloud judgment and lead to poor financial choices, whether panic-selling investments during a market downturn or making impulsive purchases. Developing a disciplined approach to finance, staying focused on long-term goals, and making decisions based on careful analysis rather than emotions can help you avoid this pitfall.
Neglecting to Plan for Retirement
Many people delay planning for retirement, thinking they have plenty of time. However, the earlier you begin saving for retirement, the better. Failing to prepare adequately for retirement can lead to financial insecurity in your later years. Contribute frequently to retirement accounts, such as 401(k) or IRAs, and take advantage of employer matches and tax benefits. Planning early ensures you have sufficient funds to maintain your lifestyle after you stop working.
Improving financial status requires careful planning, discipline, and a commitment to making informed decisions. Taking proactive measures to deal with your finances effectively will help you achieve long-term stability and prosperity.